How to Understand an EMI Before Taking a Loan
Compare monthly payments with the total cost of borrowing.
October 20, 20265 min read
How to get started
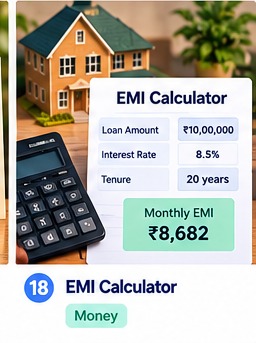
1. Check the loan amount
Use the amount you expect to borrow.
2. Check the interest rate
Confirm whether the rate is annual and fixed or variable.
3. Choose the loan term
A longer term may lower the monthly payment but increase total interest.
4. Include other charges
Review processing fees, insurance and other disclosed costs.
5. Compare total cost
Review monthly EMI and total repayment before deciding.
Example
Compare two offers using the same loan amount and term, then review the lender’s official repayment schedule before signing.
Helpful reminder: This guide is general information. Confirm important requirements with the relevant official source. Tool results may be incomplete and do not guarantee a particular outcome.
Frequently asked questions
Is a calculator quote the lender’s final offer?
No. It is an estimate; confirm the final terms with the lender.
Does a lower EMI always mean a cheaper loan?
No. A longer repayment term can increase total interest.